
Aspire Account Center
- Rating
- 3.3
- Downloads
- 500.00K
- Content Rating
- Everyone
Aspire Account Center - Screenshots
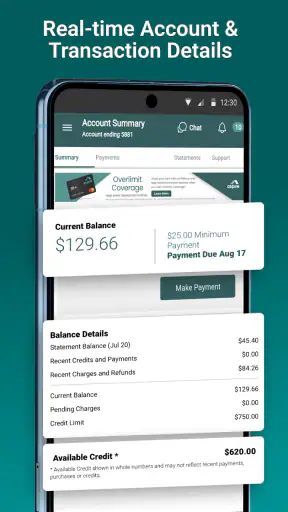
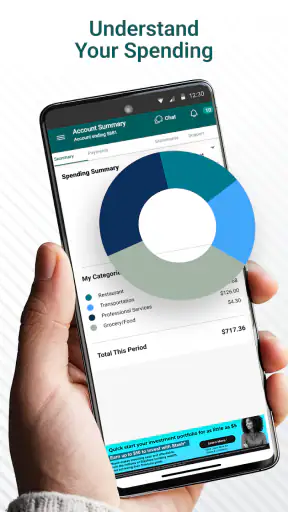
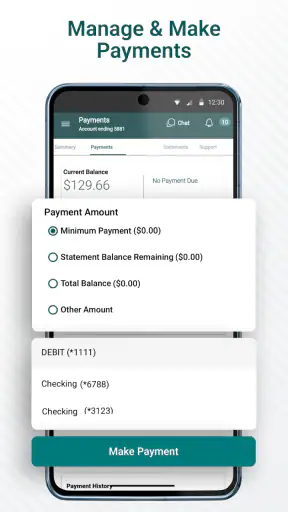
Pros
- Centralizes profile
- account
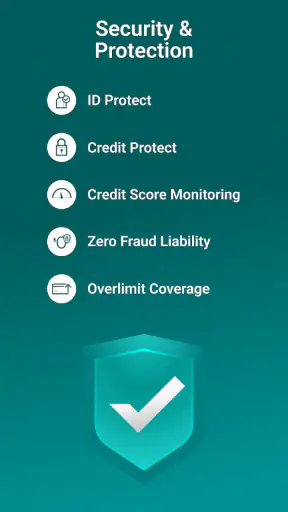
- and security settings in one place.
- Makes it easier to review personal information and account preferences.
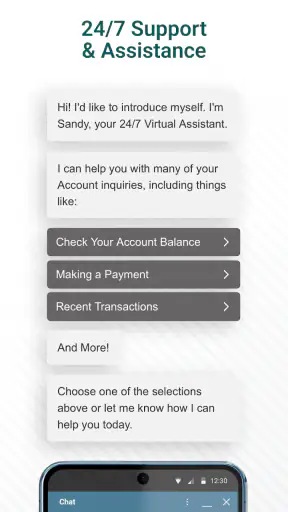
- Provides convenient access to Aspire-related support and account tools.
- Helps users manage notification and communication preferences.
- Useful companion for customers who prefer handling account tasks on mobile.
Cons
- Some features may require an eligible Aspire account or membership.
- The app’s usefulness depends on which Aspire services you already use.
- Certain account changes may still require contacting customer support.
- Login or verification issues can temporarily block access to account tools.
- Updates may change the layout or availability of individual settings.
Aspire Account Center - Description
- App Name
- Aspire Account Center
- Package Name
- com.atlanticus.aspire
- Developer
- Atlanticus Services
- Category
- Finance
- Last Updated
- Jun 25, 2019
- Version
- 4.22.47-6102
Managing a credit card from a phone sounds simple until a household has to coordinate payments, check available credit, and keep personal account details separate. I found Aspire Account Center most useful as a focused mobile place for handling an Aspire credit card rather than as a complete household finance system. That distinction matters: it can make one account easier to monitor, but it is not a shared budgeting board for everyone in the home.
The app is a free finance app from Atlanticus Services, and its purpose is straightforward: give cardholders a way to manage their credit cards from one place. In everyday use, I would treat it as a companion to the card itself, especially for checking the account while away from a desktop browser. It is available for Everyone, runs on Android six and later, and has passed half a million installs. Those details make it accessible to many households, but accessibility should not be confused with unrestricted shared access.
How Aspire Account Center works in a shared household
A realistic example is a couple using one Aspire card for groceries and recurring bills. One person may make the purchase, while the other wants to check the balance before making another payment. Having the account center on a phone can reduce the need to wait for a computer or search through paper statements. I like that kind of convenience because it turns a quick account check into something that can happen during an ordinary shopping trip.
There is an important boundary, though. The app centers on the card account, not on household finances as a whole. I would not expect it to combine several unrelated cards, track cash spending, divide a bill between family members, or replace a budgeting app. If your goal is to see a complete picture of rent, utilities, savings, loans, and multiple cards, a broader finance tool will usually be a better fit.
For a shared-device situation, I would be careful about simply signing in and leaving the account open. A phone used by several people can expose sensitive financial information to the next person who picks it up. The practical approach is to decide who genuinely needs access, use the device’s own security protections, and sign out or lock the app when appropriate. The app can help with account management, but it cannot make a household’s trust decisions for you.
That is one of the first useful lessons I took from using a card-management app like this: convenience is strongest when access is deliberate. A partner who needs to review a purchase may need a different arrangement from a teenager who occasionally carries the physical card. Keeping those roles separate avoids turning a simple balance check into unnecessary exposure of account information.
Setup should begin with account boundaries
Before installing it on a family tablet or a phone that stays in a common room, I would decide whether that device is really personal. A finance app is not like a weather widget or a recipe app. Even when the household trusts one another, saved sessions and visible balances can create awkward situations. I would use a personal device for the primary account and only consider a shared device when everyone understands exactly who may open it.
The developer is Atlanticus Services, and the app is designed around Aspire card management. That means the first question is not whether every member of the household can use it, but whether the person setting it up is the cardholder who should be managing the account. If someone else only needs information about a purchase, a conversation or a separate household record may be safer than handing over direct access.
I also recommend preparing the information needed to identify the account before beginning setup, rather than attempting it while standing in a checkout line. A calm setup gives you time to review what is displayed, confirm that you are in the intended account, and choose a sensible routine for closing the session afterward. That may sound basic, but financial apps reward careful habits more than hurried tapping.
Another boundary is device compatibility. The current version is 4.22.47-6102 and requires Android 6.0 or newer. For most relatively recent Android phones that should not be a major obstacle, but older household devices can be a different story. If an old tablet is being repurposed for family finances, check its Android version before planning around it. A shared workflow is only useful if the chosen device can actually run the app.
I would also avoid treating the app as the only place where the account exists. A phone can be lost, damaged, offline, or unavailable to the person who normally manages it. Keeping a general awareness of payment dates and account responsibilities outside the app is sensible. The application can make access easier, but it should support a household routine rather than become the household routine by itself.
Coordinating payments without turning the app into a family dashboard
The strongest household use case is coordination around one Aspire card. One person can review the account before a planned purchase, while another can check whether a recent transaction has appeared. This is especially helpful when several people use the same card and memory is unreliable. Instead of asking, “Did we already spend on that?” someone can check the account and make a more informed decision.
My tip is to agree on a simple division of responsibility before relying on the app. For example, one person can be responsible for reviewing activity, while another handles the payment routine. The exact arrangement is up to the household, but naming the responsibility prevents the common problem where both people assume the other person checked the account.
The trade-off is that the app is not a substitute for communication. A visible account does not explain why a purchase was made, whether a charge is expected, or whether a payment has already been discussed. If a household uses the same card for personal and shared expenses, I would keep a short note or shared record for unusual purchases. The app can show account information; it does not automatically create context around that information.
This is also where Aspire Account Center differs from a typical budgeting app. A budgeting service may focus on categories, spending plans, and several accounts in one overview. This app is more focused on the Aspire credit-card relationship. I prefer that narrower purpose when I want a quick card check without navigating a large financial dashboard. I would choose the broader alternative when the main task is planning the household’s entire month.
There is a second comparison worth making with a mobile browser. A browser can be useful when you need a wider account-management environment or when you are on a computer already. The dedicated app makes more sense when the task is a quick phone-based check. I would not install it merely because an app exists; I would install it if frequent mobile access to this particular card is part of my routine.
For a household with several Aspire cards or several people who each manage separate accounts, I would think carefully before assuming one sign-in solves everything. The app’s central idea is managing credit cards from one place, but personal account boundaries still matter. Mixing accounts on a shared phone can make it harder to know whose information is currently visible and who is responsible for the next action.
Age, trust, and the difference between carrying a card and managing it
The Everyone content rating makes the app broadly suitable from a store-rating perspective, but that does not mean every child should be given direct access to a credit-card account. I see a clear difference between a young person using a card under household rules and that person opening the account center. The latter involves financial information and account responsibility, so the adult cardholder should decide what access is appropriate.
For a teenager who occasionally shops for the household, I would use the app as an adult’s checking tool rather than a child’s financial dashboard. The adult can review the account before sending the teenager to the store, then discuss the spending limit separately. This keeps the practical task—checking whether the card is available—away from the more sensitive task of exposing account details.
For older children or relatives who share financial responsibilities, trust needs to be specific rather than assumed. Ask who needs to see the account, what they need to do, and whether the device is protected. A shared household may be close-knit, but that does not remove the need for clear account boundaries. In my view, the best use of this app is with a small number of responsible adults who understand the card arrangement.
I would also be cautious with guests, temporary caregivers, or anyone borrowing the device. A finance app should not be treated like a general household utility that everyone can open. If the phone changes hands often, the risk is less about the app’s category rating and more about simple exposure: a balance, transaction history, or account screen may be visible at the wrong moment.
That does not make the app unsuitable for families. It simply means the household should establish a rule before installation: who uses the app, on which device, and for what purpose. A clear rule is more useful than assuming the presence of a finance app will somehow organize everyone’s behavior.
Where the app earns its place—and where it does not
I see three particularly useful workflows. The first is a pre-purchase check: before using the Aspire card for a larger household expense, open the account center and confirm the current account picture rather than relying on memory. The second is a post-purchase review: after several family members have used the card, check the activity so an unexpected charge can be noticed sooner. The third is responsibility handoff: one adult can review the account while another prepares the household’s payment plan.
These workflows are valuable because they connect the app to specific moments. They are better than opening it aimlessly every day and hoping it will solve broader money-management problems. I would use it as a checkpoint in a routine, not as a replacement for a budget, a shared note, or a conversation about spending.
One limitation is the narrowness that makes the app easy to understand. If you want investments, bank accounts, cash envelopes, debt planning, or detailed household categories in the same place, this will likely feel incomplete. A full finance platform may offer more context. The cost of that extra breadth is often more setup and more information to sort through, so the better choice depends on whether your priority is a quick card view or comprehensive planning.
Another point is that a rating of 3.3 from around two thousand ratings suggests a mixed user experience rather than universal satisfaction. I would not treat that number as a verdict by itself, but I would set expectations accordingly. Finance apps can feel excellent when the account is easy to access and frustrating when a sign-in, device, or account-specific issue interrupts a time-sensitive task. The app is worth trying for an Aspire cardholder, but I would keep a backup way to manage important responsibilities.
The free price removes one obvious barrier to trying it, which is helpful if you already have an Aspire card and want mobile access. Still, “free” does not mean the app is a complete financial service or that it eliminates the responsibilities attached to the card. I would judge it by whether it saves me time during account checks, not by expecting it to improve spending habits automatically.
Someone who rarely uses a smartphone for financial tasks may be happier with the usual web-based account access. Someone who wants a unified view of several financial institutions should look at a multi-account finance app instead. And someone seeking a family spending system should choose a tool built around shared budgeting rather than forcing a card-management app into that role.
My household verdict
After considering the way a household would actually use it, I see Aspire Account Center as a practical, focused companion for Aspire credit-card management. I would recommend it to the adult cardholder who wants a convenient mobile checkpoint for account activity and routine coordination. Its value is clearest when one person manages the account and another household member occasionally needs to coordinate a purchase or understand the card’s current situation.
I would not recommend installing it casually on a communal device with an always-open session. The app can support shared responsibility, but it should not erase personal account boundaries. Adults should decide access, younger users should not be given financial visibility simply because the app is rated Everyone, and households should keep their broader budget organized somewhere suited to that job.
Atlanticus Services has kept the product’s role clear: it is a finance app for managing Aspire credit cards in one place. With over five hundred thousand installs and a free download, it is accessible enough to try if that is the account you use. My advice is to begin with one concrete purpose—checking activity, coordinating a purchase, or keeping up with account responsibilities—and see whether it fits your routine.
My final recommendation is cautious but positive: use it for focused card access, protect the account on shared devices, and do not mistake it for a household budget. For the right Aspire cardholder, that narrow focus is a strength. For anyone looking for complete family money management, a broader alternative will serve better.
FAQ
What is Aspire Account Center used for?
Aspire Account Center is designed to help users manage and monitor their Aspire-related account information from one place. Depending on the services available in your region, it may provide access to profile details, account activity, statements, payment information, support resources, and security settings. The exact tools you see can vary according to your Aspire product and account type.
Who can use Aspire Account Center, and how do I sign in?
Access is generally intended for existing Aspire customers or users with an eligible Aspire account. During sign-in, you may need the email address, phone number, username, password, or verification code associated with your account. New users might need to complete registration through Aspire first. If your credentials are rejected, use the official recovery option rather than repeatedly attempting to log in.
Is Aspire Account Center safe for managing personal or financial information?
The service is intended to provide secure access to account information, but users should still take normal precautions. Download it only from an official app store or use Aspire’s verified website, keep the application updated, and avoid signing in over unsecured public networks. Never share passwords or one-time verification codes, and contact official support if you notice unfamiliar activity.
What should I do if I cannot log in or the app is not working correctly?
First, check that your internet connection is stable and that you are entering the correct login details. Updating the app, restarting your device, or clearing temporary app data may resolve minor problems. If verification messages are delayed, confirm that your contact information is current. Persistent account, password, or access issues should be handled through Aspire’s official customer support channels.
Are there any fees for using Aspire Account Center?
The account-management application itself may be available without a separate download charge, but using it does not automatically remove fees connected with your underlying Aspire product or service. Transaction, subscription, transfer, card, or other account charges may still apply according to your agreement and location. Review the applicable terms and fee schedule before relying on the service for financial management.


